

Types of storm roof damage refer to the specific ways a roof is harmed by severe weather, including hail, wind, water intrusion, and debris impact. Hail alone causes over $14 billion in U.S. property damage annually. Wind, water, and falling debris add billions more each year. Knowing which type of damage your roof has sustained is the first step toward accurate repair planning, cost estimation, and a successful insurance claim. This guide breaks down each damage category so you can assess your roof with confidence and act before small problems become expensive ones.
1. What are the common types of storm roof damage?
Storm roof damage falls into five main categories: hail, wind, water intrusion, impact from debris, and structural damage. Each type has distinct visual signs and different consequences for your roof's ability to shed water and protect your home. Identifying the right category matters because insurers, contractors, and inspectors all use specific criteria to evaluate and price repairs.
The five categories at a glance:
- Hail damage: Dents, granule loss, and bruised shingles that compromise waterproofing
- Wind damage: Lifted, creased, or missing shingles and displaced ridge caps
- Water intrusion: Ceiling stains, damp insulation, active leaks, and mold risk
- Impact damage: Punctures, cracks, and surface breaks from branches or debris
- Structural damage: Hidden failures in decking, fascia, underlayment, and framing
Each category requires a different repair approach and carries different implications for types of roof damage coverage under a standard homeowner's policy. Knowing which type you are dealing with before calling your insurer saves time and prevents claim mistakes.
2. How to identify hail damage on your roof
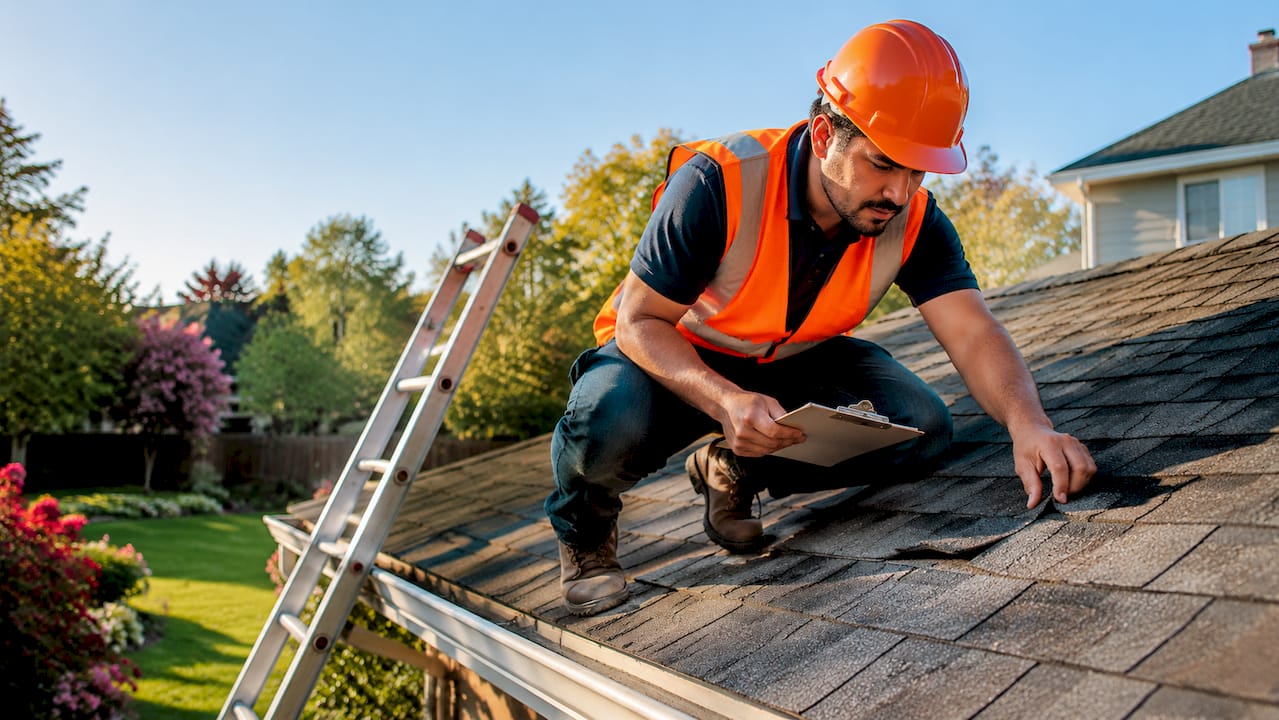
Hail damage is the most frequently claimed weather-related roof damage in the United States. The key visual sign is a sharp-edged circular dent on shingles, often accompanied by a dark center where granules have been knocked away. These marks appear in clusters or patterns that follow the storm's path across the roof.
Roughly 70% of hail damage is not visible from the ground. That statistic means a roof can look fine from the street while sustaining significant hidden harm. A professional inspection is the only reliable way to confirm hail impact.
Hail also leaves evidence on other surfaces. Check aluminum gutters, downspout caps, and metal flashing for fresh dents. Consistent damage patterns across multiple roof components are what insurance adjusters look for when validating a claim.
Pro Tip: Photograph dents on gutters and metal vents alongside shingle damage. Adjusters treat corroborating evidence on multiple surfaces as strong proof of a legitimate hail event.
3. How to tell hail damage apart from normal shingle wear
Normal shingle wear and storm damage look similar to an untrained eye, but they follow completely different patterns. Normal wear shows a broad, even aging pattern across the entire roof surface. Storm damage forms clusters, lines, or patches that are inconsistent with the roof's overall condition.
Three reliable ways to differentiate the two:
- Edge sharpness: Hail impact marks have non-weathered, sharp edges. Wear-related granule loss has soft, rounded edges that developed gradually.
- Distribution: Storm damage concentrates on one roof slope facing the storm. Wear distributes evenly across all slopes.
- Corroborating evidence: Hail leaves marks on gutters, vents, and AC units. Normal wear leaves none.
Functional damage is the standard that determines insurance eligibility. Cosmetic surface marks that do not affect water-shedding performance rarely qualify as insurable storm damage. Knowing this distinction before you file protects you from a denial based on misclassified damage.
Pro Tip: Ask your inspector to photograph the damage pattern from multiple angles. A clear pattern map is far more persuasive to an adjuster than a single close-up photo.
4. Recognizing wind damage and its effect on roof performance
Wind damage begins at sustained speeds of 50–60 mph, when uplift forces become strong enough to displace ridge caps, tear shingles, or strip flashing from valleys and edges. Hurricane-related damage averages over $22 billion annually in the U.S., with peak activity from august through october. That scale reflects how destructive wind events are even on roofs that appear intact after a storm.
Signs of wind damage follow a clear progression:
- Lifted shingles: Edges curl upward, breaking the seal strip and exposing the underlayment below.
- Wind creases: A visible crease or fold across a shingle indicates it was bent back by uplift. This is distinct from gradual curling caused by age.
- Missing shingles: Entire tabs or shingles are gone, leaving bare decking exposed to rain.
- Flashing separation: Metal flashing around chimneys, skylights, or valleys pulls away from the roof surface.
- Ridge cap displacement: The cap shingles along the roof peak are the first to lift in high winds.
Pro Tip: Never assume a roof is wind-tight just because no shingles are missing. A creased or re-sealed shingle can fail in the next storm. Get a professional wind damage assessment before the next rain event.
Structural risk increases sharply when flashing separates or decking is exposed. At that point, the roof is no longer performing its core function and requires immediate professional evaluation.
5. Common water-related storm damage and its hidden consequences
Water intrusion is the most deceptive type of storm roof damage because the entry point and the visible symptom are rarely in the same location. Water travels along rafters and decking before dripping onto insulation or ceiling drywall, sometimes appearing several feet from the actual breach.
Signs that water has entered your home after a storm include:
- Yellowish or brown ceiling stains that spread or darken after rain
- Musty odors in the attic, indicating damp insulation or early mold growth
- Active drips or wet spots on interior walls during or after a storm
- Soft or sagging drywall in upper-floor ceilings
Ignoring early water intrusion signs escalates interior damage and raises mold risk significantly. Mold can establish within 24–48 hours in damp insulation, turning a manageable repair into a full remediation project. If you suspect water entry, a partner resource like water damage restoration specialists can assess interior moisture before it spreads.
Roof penetrations are the most vulnerable entry points. Vents, skylights, pipe boots, and chimney flashings all rely on tight seals that storms can break. Inspect these areas first after any significant weather event.
6. Impact and structural damage from debris and falling objects
Impact damage occurs when tree branches, large hail stones, or airborne debris strike the roof with enough force to puncture, crack, or compress roofing materials. The difference between cosmetic and functional impact damage determines whether a repair or a full replacement is needed.
| Damage Type | Visible Sign | Functional Risk |
|---|---|---|
| Surface dent | Shallow depression, no material breach | Low, monitor for granule loss |
| Puncture | Hole through shingle and underlayment | High, immediate water entry risk |
| Decking compression | Soft spot underfoot, no visible hole | High, structural integrity compromised |
| Fascia crack | Split or broken fascia board at roof edge | Medium, water entry at eave line |
Structural damage often originates from hidden failures such as flashing separation or underlayment compromise that homeowners cannot detect visually. Walking on a damaged roof after a severe storm is discouraged until a professional confirms the decking is structurally sound. A soft or spongy feeling underfoot signals decking damage that requires immediate attention from a qualified contractor.
Structural assessment extends beyond visible defects. Rafter connections, decking integrity, and underlayment condition all factor into whether a roof is safe and functional after a major impact event.
Key takeaways
Accurately identifying the type of storm roof damage is the single most important step before filing an insurance claim or scheduling repairs.
| Point | Details |
|---|---|
| Hail damage needs professional eyes | 70% of hail damage is invisible from the ground; always get a professional inspection. |
| Wind damage starts at 50–60 mph | Look for lifted shingles, wind creases, and flashing separation after high-wind events. |
| Water intrusion hides its entry point | Ceiling stains and musty odors appear far from the actual roof breach. |
| Functional vs. cosmetic damage matters | Only damage that affects water-shedding performance qualifies for most insurance claims. |
| Document immediately after the storm | Photo evidence of consistent damage patterns across multiple surfaces strengthens claim approval. |
What I've learned from 25 years of storm damage assessments
Homeowners consistently make the same mistake after a storm: they look at the roof from the driveway, see no missing shingles, and assume everything is fine. That assumption costs them thousands of dollars every year.
The damage that causes the biggest problems is almost always the damage you cannot see from the ground. A creased shingle looks intact. A compromised flashing seal looks dry. A soft spot in the decking feels normal until the next heavy rain. By the time the ceiling stain appears, the repair bill has doubled.
The other pattern I see constantly is homeowners waiting too long to document. Insurance claims require proof that damage was sudden and storm-related, not gradual. If you wait three weeks to photograph your roof after a hail event, an adjuster has every reason to argue the damage was pre-existing. Get photos within 24 hours of the storm, even if you are not sure whether to file a claim.
The distinction between cosmetic and functional damage is where most claims succeed or fail. Adjusters are trained to classify borderline damage as cosmetic. A HAAG-certified inspector knows how to document functional impairment in language that holds up in the claims process. That expertise is not a luxury. It is the difference between a paid claim and a denial.
— Ebben
Exteriorgenie is ready when storms hit Lexington, SC
Storm damage does not wait for business hours, and neither does Exteriorgenie. As a veteran-owned roofing company serving Lexington, SC, Exteriorgenie provides 24/7 emergency response, HAAG-certified inspections, and hands-on insurance claim assistance to help you document and file with confidence.
Whether your roof took a hail hit, lost shingles to wind, or is showing signs of water intrusion, Exteriorgenie's inspectors assess every damage type with the precision your claim requires. The team also offers flexible financing options so repairs move forward without delay. Contact Exteriorgenie for a storm damage roof repair assessment and get your home protected before the next storm season arrives.
FAQ
What are the main types of storm roof damage?
The five main types are hail damage, wind damage, water intrusion, impact damage from debris, and structural damage to decking or underlayment. Each type has distinct visual signs and requires a different repair approach.
Does insurance cover all types of storm roof damage?
Most homeowner policies cover sudden storm-related damage, but only when it is functional rather than cosmetic. Damage that does not affect the roof's ability to shed water is frequently excluded from claims.
How do I know if my roof has hail damage?
Look for sharp-edged circular dents on shingles and fresh dents on gutters, vents, and metal flashing. Because roughly 70% of hail damage is not visible from the ground, a professional inspection is the most reliable confirmation method.
When should I call a roofer after a storm?
Call within 24–48 hours of a storm if you notice missing shingles, ceiling stains, or visible debris impact. Early inspection preserves your documentation window and prevents water intrusion from escalating into mold damage.
What is the difference between cosmetic and functional roof damage?
Functional damage degrades the roof's water-shedding performance and qualifies for insurance consideration. Cosmetic damage, such as minor surface marks or color changes, does not affect roof performance and is typically not covered under standard policies.